


A fire, hailstorm, or flood already cost you enough. You shouldn't have to fight your own insurance carrier just to get what your policy promised. When an insurer denies, delays, or lowballs a property claim, Omar Ochoa Law Firm steps in on behalf of Texas homeowners and business owners, and we're prepared to take the fight to court. Our exceptional Austin property insurance attorneys know how carriers build a case against a claim, and we know how to dismantle it.
Free Consultation
Available 24/7
No Fee Until We Win

Insurance companies count on policyholders accepting whatever number an adjuster hands them. When a claim gets denied, delayed, or settled for far less than it's worth, that strategy only works if you let it.
Our Austin property insurance attorneys represent homeowners and business owners against carriers who use paperwork and policy language to avoid paying what's owed. We dig into the tactics insurers rely on to shrink a payout, and when a carrier won't honor its policy, we're ready to file suit and argue the case in front of a jury.
Here's what property owners get when they work with us:
Whether you're a homeowner in Austin or a business owner anywhere in Texas facing a denied or underpaid property claim, our team is ready to help. Contact us today at (956) 253-3121 or submit a request form for a free consultation.
Request a Free Case Review
We are available to assist you 24 hours a day!
Need help right away? Call us!
(956) 253-3121


Omar Ochoa Law Firm represents Texas property owners in a wide range of first-party insurance disputes against carriers who unfairly deny, delay, or underpay valid claims. Below are the property insurance issues we see most often, each with its own coverage rules and common carrier tactics.

When a fire, storm, or other covered event forces your business to close temporarily, business interruption insurance can help cover lost income, operating expenses, and additional costs. These claims often require careful documentation to prove the financial impact on the business.

Texas law requires insurance companies to act honestly and fairly when handling property insurance claims. If your insurance company denies your claim without a valid reason, delays payment unreasonably, or uses deceptive practices, you may have a bad faith insurance claim. This could entitle you to compensation beyond the policy limits.

Property damage claims are the core of what we handle for Austin homeowners and business owners. These claims can arise from many events, including fires, storms, floods, and accidents. Accurately documenting the damage, understanding your policy coverage, and negotiating with the insurance company are essential steps in these claims.

Homeowners insurance protects your home and belongings from covered perils. Austin homeowners facing a property insurance dispute often see disagreements about the value of damaged property, the need for certain repairs, and the interpretation of policy exclusions.

Businesses rely on commercial property insurance to protect their buildings, equipment, and inventory. These policies can be complex and may include business interruption coverage and other provisions that require careful review.

Fire damage claims often extend beyond the immediate destruction to include smoke damage, water damage from firefighting efforts, and potential health hazards from soot and other residues. A thorough property damage claim should account for all of it, not just what's visible on the surface.

High winds from storms and tornadoes can cause significant property damage. Disputes in wind damage claims often center around the cause of the damage and the extent of necessary repairs.

Water damage can result from a variety of sources, including burst pipes, leaking roofs, and appliance malfunctions. It's important to take prompt action to mitigate water damage and thoroughly document the affected areas to support your property insurance claim.

Floods are often excluded from standard homeowners insurance policies. Separate flood insurance policies are typically required to cover losses from floods. These policies come with specific requirements and limitations that policyholders need to understand.

Hailstorms can cause major damage to roofs, siding, and vehicles. Insurance companies may try to downplay the severity of hail damage or offer repair solutions that don't fully address the problem.

Hurricanes and tornadoes can cause catastrophic devastation to property. In these situations, understanding your policy's coverage for temporary housing, debris removal, and other related expenses is paramount.
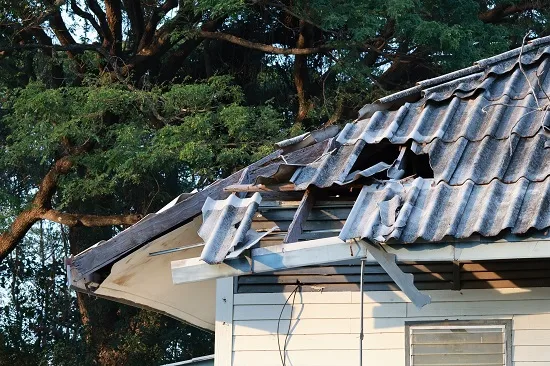
Roof claims are among the most disputed property insurance claims in Texas. Carriers frequently attribute storm-related roof damage to "wear and tear" or pre-existing conditions to avoid paying for a full replacement, even when wind or hail caused the loss.
Call Today for a Free, No-Strings Consultation
Let our skilled Austin bad-faith insurance lawyers help you get the coverage you deserve. Contact us at (956) 253-3121 to schedule a free case evaluation.
Texas law requires insurance providers to act in good faith when handling property claims. Unfortunately, some insurance companies engage in bad faith tactics to avoid paying what they owe on a property damage claim. Here are some red flags that your insurance carrier may be acting in bad faith:
If you recognize any of these signs, don't wait to take action. Contact the experienced property insurance litigation attorneys at Omar Ochoa Law Firm. We'll help you understand your rights and fight to get you the full compensation you deserve.
Cut through the confusion and get the help you need with the assistance of our accomplished property insurance lawyers in Austin.
Dealing with a property insurance claim after a loss can be stressful. Here's how our process works, from the moment you contact us to the moment your case is resolved:
With Omar Ochoa Law Firm on your side, you'll have a dedicated team looking out for your interests at every step of the legal process.
Get Your Free Case Review
Don't settle for less than you deserve - let us fight for you.
No Recovery, No Fee. Guaranteed.
Call us (956) 253-3121 today.
Want to hear more about how we help and what we do? Don’t just take our word for it. Read our real client reviews and testimonials - and see videos from our real former clients.


Our attorneys represent homeowners and business owners throughout Central Texas, from properties in downtown Austin to homes and businesses in the surrounding communities, whenever storms, hail, or fire cause a loss significant enough to bring a carrier into the picture.
A denied roof claim or a lowball fire settlement isn't the end of the road. Texas law gives property owners real standing against carriers who won't pay what a policy promises, and Omar Ochoa Law Firm knows how to use it. Schedule a free consultation to find out what your claim is really worth.

Available 24/7
No fees unless we win
Se Habla Español
Texas doesn't set one single statewide deadline for reporting a property claim. Most policies contain language that require "prompt" notice, and waiting too long can itself give a carrier grounds to deny. If a dispute ends up in court, breach-of-contract claims on a policy generally must be filed within four years of the loss. The safest approach is to report the damage as soon as it happens and keep dated records of every communication with your carrier.
Under the Texas Prompt Payment of Claims Act (Tex. Ins. Code § 542.055), your carrier must acknowledge your claim, start its investigation, and request any documents it needs within 15 calendar days of getting notice of the loss.
Flood damage is excluded from standard homeowners and commercial property policies in Texas, no matter which carrier you have. Covering it requires a separate flood policy, typically through the National Flood Insurance Program or a private flood insurer. Mold is handled differently: it's usually covered only when it results directly from a sudden, covered event, like a burst pipe, and even then most policies cap the payout at a mold sublimit, often in the $5,000 to $10,000 range. Texas insurers must also offer an optional buyback endorsement that raises mold coverage to 25%, 50%, or 100% of your dwelling limit. Mold caused by flooding, gradual leaks, or long-term humidity is excluded either way.
Document the damage with photos or video before making any repairs, keep receipts for any emergency mitigation work (like tarping a roof), report the loss to your carrier promptly, and avoid signing a settlement or giving a recorded statement before you understand what your claim is actually worth. An attorney can review your policy early, before the carrier's tactics shape the outcome.
Yes. You aren't required to accept a settlement offer you believe is too low. You can negotiate directly with the carrier, invoke your policy's appraisal clause to get an independent valuation, or, if the carrier is acting in bad faith, pursue a claim under the Texas Insurance Code for damages beyond what the policy would otherwise pay.
Insurance Litigation
Published:
March 28, 2024
By
Omar Ochoa


